Be yourself; Everyone else is already taken.
— Oscar Wilde.
This is the first post on my new blog. I’m just getting this new blog going, so stay tuned for more. Subscribe below to get notified when I post new updates.
Be yourself; Everyone else is already taken.
— Oscar Wilde.
This is the first post on my new blog. I’m just getting this new blog going, so stay tuned for more. Subscribe below to get notified when I post new updates.
Are you in urgent need of money? A loan is basically that you need money for a particular purpose, and you need to borrow it. A personal loan means that you require the loan for a personal purpose, and that is why you do not need to particularly mention what is your exact reason for borrowing. It depends on the institution or bank lending and your personal choice that you wish to reveal the motive behind borrowing money or not. This money borrowed from a credit union, an online lender or a bank, you have to pay back in installments or fixed monthly payments, typically over two to seven years. Generally, these personal loans are unsecured in nature and are not backed by any collateral.
Your current financial needs are met through personal loans and you do not even have to pledge any security for availing it since personal loans can be unsecured or secured. On the other hand, a secured loan requires a particular type of collateral. Most of all, the lenders provide you great flexibility for using the funds as per your requirements.
There is a direct connection between credit score and a personal loan. The chances of personal loan approval are higher when the credit score is better. Usually, banks ask for a credit score of 750 or higher for personal loan purposes. This is because the banks are at a higher risk factor if the personal loans are unsecured. Even if there is a circumstance where the borrower is not able to pay back the loan, the only thing a bank can do is to file a suit against the borrower for recovering the amount. There is not much that can be done from the banks’ side apart from that. This is the prime reason why the credit score is so crucial with respect to personal loans.
Well, definitely yes. There are many financial institutions today that offer you a personal loan even if you have a low credit score. However, they might keep the rules and regulations a bit strict for you such as charge you a higher interest rate and so on. You must ensure that you do appropriate research of the lending party and check if they are credible. Do not fall victim to scammers who take your data and never disburse your loan too. Some of the cheaters even make you pay some fees upfront by luring you with good terms and conditions. You might not even see them or your money again ever. Make sure that you are aware of the suitable interest rate that you are being offered. There are various lenders with the wrong intentions who will show you interest rates, not in terms of years, but months. In a way in which, 30% per annum is depicted at only 2.5% every month. When you compare such a rate of interest with a regular bank, you are only charged an average of 14%, which is actually 1.66% every month. These percentages might seem small, but they account for a significant difference when you calculate the interest over a long period of time. You need to beware of these scams and false tricks. On the other hand, there are various other valid options that could be availed for getting a personal loan with a low credit score such as the following:
Credit Bazaar assists you with all your credit queries right from credit cards to personal loans, to your credit score. Our team of professionals helps you to increase your credit score, get personal loans, and so on. Whenever you are stuck with a problem regarding your credit, Credit Bazaar has a solution for everything as it guides you, one step at a time, to improve your credit situation in a very relaxed and easygoing manner!
Contact Credit Bazaar and have faith in us completely for your credit health, as a good credit score can unlock all the things that you want in life!
For any queries regarding Credit Score improvement or Loan contact Credit Bazaar CR Arcade 2nd Floor, Opposite Delta Garden, Next to Shree Mahalaxmi Restaurant, Mira Road East, Thane: 401107
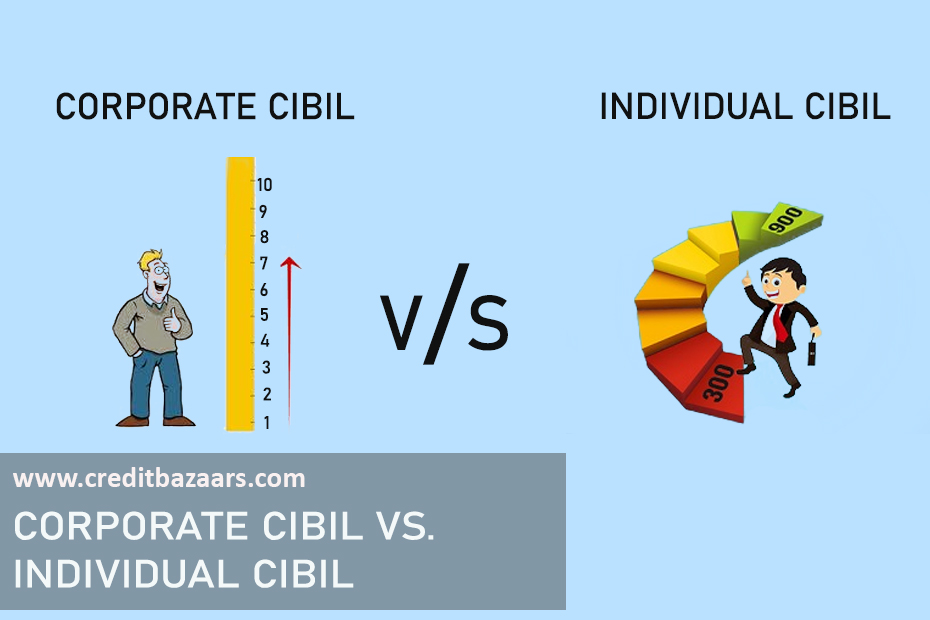
Corporate credit score rating is a 1-digit number going from 1 to 10. The closer the position of the organization is to 1, the better is the credit well being. The likelihood of missing payments of a company is indicated by a CREDIT SCORE Rank. This is the prime factor considered by the lending party while evaluation of a loan application. The better the CREDIT SCORE rank, the higher are the chances of securing a loan.
An extreme record that speaks to the money related strength of an organization that is arranged based on data got from shifted acknowledge foundations is called as Company Credit Report (CCR). This report is used by banks for evaluating the financial soundness of an organization before allowing a credit. Essentially, the past installment conduct of an association is a solid sign of its future conduct. A specific CCR incorporates different money related items. The corporate report gives all the foundation data, for example, auxiliary and parent organizations, long periods of activity, possession, and so on. The money related data of the organization is expressed in detail that decides the fitting credit levels that loan specialists can allow them to acquire. The money related history is likewise referenced including assortments, income age, reimbursements, and that’s only the tip of the iceberg.
WHAT ARE THE FACTORS THAT INFLUENCE THE COMPANY CREDIT REPORT?
Credit score assessment readies the CCR for your organization subsequent to having a decent take a gander at the characteristics and budgetary history of your organization. Here are a couple of components that sway your association’s CCR:
The credit usage proportion of an organization is spoken to by the credit to obligation proportion. It is likewise called an equalization to-restrain proportion which alludes to the measure of obligation that you at present have, versus the amount of acknowledge that is accessible for you. An a worthy representative for obligation proportion speaks to the credit use proportion of an organization. At the point when an organization is spending its obtained reserves quicker than anticipated, it demonstrates a higher credit usage proportion. This can negatively affect the CCR. A low obligation to-credit proportion is an essential piece of keeping up a solid financial assessment in the CCR.
Each organization requires activity assets to meet the everyday use of a business cycle. These accounts are profited through credits which must be paid by means of EMIs. People, just as organizations, should pay their EMIs on time as a top notch marker of money related wellbeing. There ought not be an expanded pattern in moderate installment of the commitments of the organization.
The amount of debts outstanding or the external debts can have a negative impact on a company’s CCR as credit institutions take into consideration the outstanding amount. Hence, it is crucial to maintain and keep only feasible amounts outstanding. Just focus on paying back as much as possible if you are carrying balances on your corporate credit cards. As said on the Experian website, reducing these balances will immediately impact your credit score in a positive way. If your payment history is good, you can also apply for an increased credit limit as this will improve your credit ratio in your debt-to-equity ratio. It is indicated that you should not be using any more than 20 to 30 per cent of your available credit lines at any specific time.
The size and life of an organization are significant components to be considered here. More seasoned and bigger organizations have a sound and settled budgetary history, consequently they are looked to be progressively solid in contrast with new organizations and new businesses. The recency, status, dollar sums, and recurrence of any relevant decisions, liens or insolvencies are an essential component affecting the CCR of an association.
Specific mechanical segments have a higher hazard and effect on an organization’s CCR. For example, if your organization works in the oil and gas industry which is considered of having a high instability because of global economic situations, the organization will be viewed as less trustworthy in contrast with organizations from many stable segments, for example, banking and protection. Likewise, like individual CCR, an organization’s CCR additionally works in an indistinguishable manner. On the off chance that the credit use of an organization is higher, they appear credit hungry and along these lines, it is viewed as less financially sound.
9. DISPUTE ANY INQUIRIES AND ERRORS: A great idea for improving your corporate credit score is to work with credit reporting agencies and credit card companies for the purpose of getting negative feedback eliminated from your business credit file. It is urgent to ensure that what is being accounted for on the credit report of your business is state-of-the-art and exact. Unpaid records and hard requests can influence your report adversely, in this manner, it is imperative to promptly call and question in the event that you see something on your report that ought not be there. This is a basic technique for improving your corporate financial assessment.
10. PAY FOR DELETE WITH COLLECTIONS: In case any of your debts went to collections, you have to pay attention to detail when time comes to make good with them. You have to push the agency and make sure that they delete the negative account from your business credit report. You have to right away ask for such a change because if you don’t then even paying off your debt won’t lead to a rise in your credit score. This will occur if your credit report still shows a recorded history of negative accounts. In order to increase your credit score now, you immediately have to get the negative account history removed for your report completely. If they won’t agree for ‘pay for delete’, there is actually no need for paying the collection agency since your goal of improving the credit score is not fulfilled. This happens as it will affect the credit score irrespective if it is paid or not.
11. TRADE LINES: If your company is in requirement of inventory or supplies from outsourced vendors, then it will be very advantageous for your business to establish a trade line of credit. The trade done with the vendors is usually on a monthly basis. That is why a great way to start credit improvement is to ask them to report to the credit agencies. There are high chances that trade credit will be your business’ very first line of credit, so you really have to make sure that they are reporting. Before they give you a credit score, most of the credit agencies make sure that you have at least four open and active trade lines. For getting started, these might seem like too many, but you want the agencies to measure your financial reputation based on numerous varying aspects. Your business credit score will be more accurate if they have a good amount of information. Even a single history of credit from one particular vendor can do wonders for your credit score. However, multiple parties of vendors and suppliers reporting your outstanding record of payments is the best method to improve yourbusiness credit score.
12. APPLYING FOR BUSINESS CREDIT CARDS: The loan specialists will lead an individual credit check if your business is new or has too little installment history to appear. All things considered, credit is given to satisfy your necessities, so it’s anything but an awful thing in that capacity, in any case, you must be shrewd where precisely you are spending it. The financial record of your business needs to show to your banks that you are utilizing credit offices, yet you are not maximizing on your charge cards. A tolerable and satisfactory proportion is around 20 percent. If you notice that you require more than 20 percent of your credit each month, then it is better to increase the limit or apply for another credit card. It will help you receive benefits the most from it as well as keeping your credit ratio low.
13. USING CREDIT WISELY: As a businessperson, you will have numerous types of credit to choose from for your business such as business credit cards, lines of credit from trade vendors, and bank loans. Be it whatever credit courses of action you decide to choose, simply ensure that you carry on honestly. At the point when you speak to that your head is spot on your shoulders, utilizing credit carefully, the business credit reports will begin to imply this reality. Also, make sure to put your business name rather than your own name, at whatever point you use credit. At the point when you are propelling a startup, you may need to blend your business and individual accounts, which is really unavoidable. Nonetheless, over some stretch of time, you should isolate them as doing this will in the long run make your business record of loan repayment more grounded.
14. SETTING CREDIT GOALS: Various ways are available for improving your credit situation, but at the same time there are a number of avenues available to you which can easily make you overwhelmed. The best thing is to check and scrutinize your financial situation closely and set for yourself some reasonable credit goals. Decide for yourself the credit score you are aiming to achieve and what it will mean for your credit health and for your enterprise as a whole. Understanding this entire scenario, will give you some solid vision to hold and work towards, and also keep you disciplined and focused at the same time.
15. DO NOT INDULGE IN RISKY ACTIVITIES: The best technique where your credit rating assessment can be improved is to abstain from reveling any unsafe activities in any case. At the point when you realize an activity could cut down your score just as alarm off your card guarantors or leasers, abstain from taking an interest in that specific budgetary action. On the off chance that you feel a specific business action could bring you present or future cash worry, pull out and don’t include yourself in the equivalent anyway energizing it might appear.
We all know that knowledge is power, and understanding and gaining knowledge about your corporate credit score is financial power. Credit Bazaar allows you to check your credit score, provides credit summary, counseling, fraud protection, and assistance for improving credit score which can be very valuable to your business.
This is an example post, originally published as part of Blogging University. Enroll in one of our ten programs, and start your blog right.
You’re going to publish a post today. Don’t worry about how your blog looks. Don’t worry if you haven’t given it a name yet, or you’re feeling overwhelmed. Just click the “New Post” button, and tell us why you’re here.
Why do this?
The post can be short or long, a personal intro to your life or a bloggy mission statement, a manifesto for the future or a simple outline of your the types of things you hope to publish.
To help you get started, here are a few questions:
You’re not locked into any of this; one of the wonderful things about blogs is how they constantly evolve as we learn, grow, and interact with one another — but it’s good to know where and why you started, and articulating your goals may just give you a few other post ideas.
Can’t think how to get started? Just write the first thing that pops into your head. Anne Lamott, author of a book on writing we love, says that you need to give yourself permission to write a “crappy first draft”. Anne makes a great point — just start writing, and worry about editing it later.
When you’re ready to publish, give your post three to five tags that describe your blog’s focus — writing, photography, fiction, parenting, food, cars, movies, sports, whatever. These tags will help others who care about your topics find you in the Reader. Make sure one of the tags is “zerotohero,” so other new bloggers can find you, too.
Have a WordPress.com account? Log in now.

